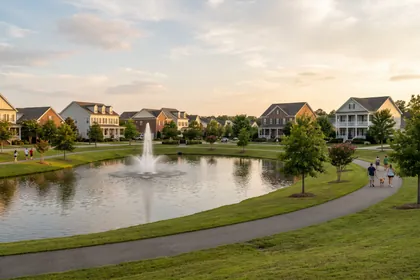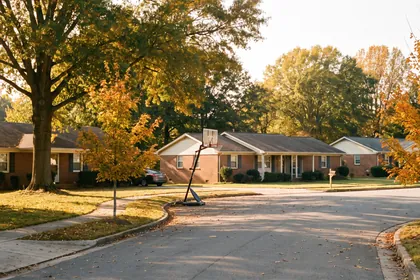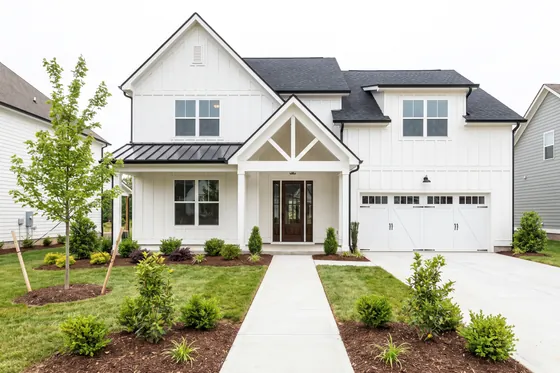
$585,000asking
- 4 bd
- 3 ba
- 2,980 sq ft
1902 Fernbright Lane
Holly Springs · Modern farmhouse
Brand new, and a note about buying new construction
Where we work
Street plans are drawn from each area's own coordinates. They show the shape of a place, not a property — no home on this site sits at a real address.
Wake & Johnston counties, NC
Everyone shows you the same homes. What changes the outcome is starting from the payment you would still be happy with in February.
Start where you actually are
On the market now
$585,000asking
Holly Springs · Modern farmhouse
Brand new, and a note about buying new construction
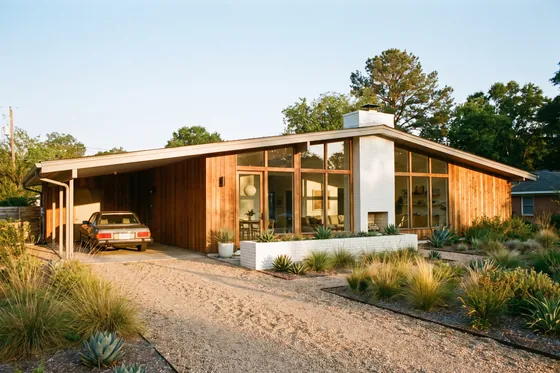
$1,195,000asking
Five Points, Raleigh · Ranch with 2019 second storey
A 1952 ranch that grew a full second storey in 2019
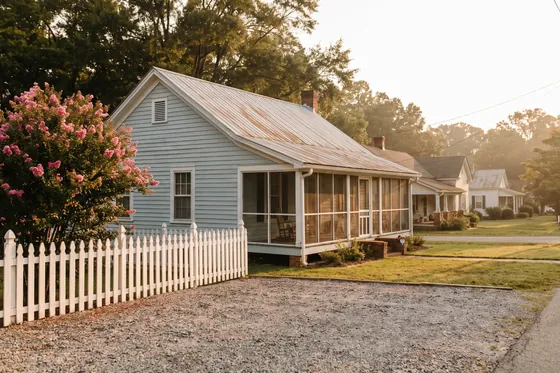
$485,000asking
Mordecai, Raleigh · Cottage
Three-bedroom cottage under $500k, four blocks from the shops
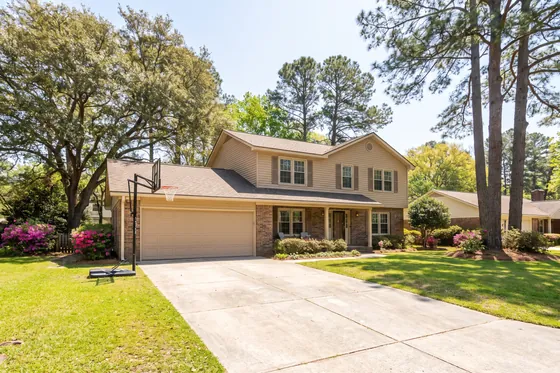
$512,000asking
Holly Springs · Two-storey traditional
Four bedrooms, a fenced yard, and a greenway gate at the back
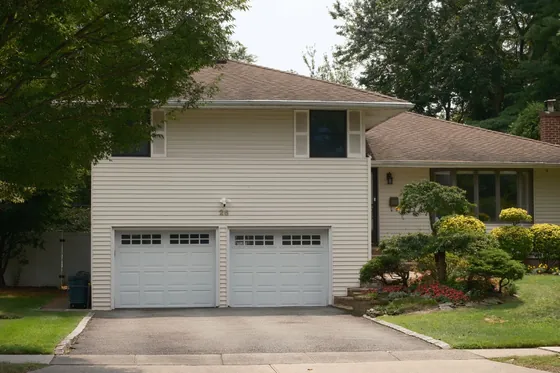
$665,000asking
Historic Oakwood, Raleigh · Four-square
A 1912 four-square, three blocks from the Governor’s Mansion
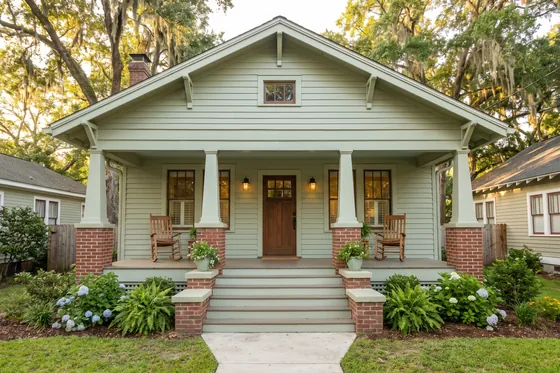
$529,000asking
Brier Creek, Raleigh · Craftsman
Built 2018, fenced yard, and a 2023 deck already in
Place first
Every description below is about the housing: when it was built, how big the lots are, what the streets do, whether there is an HOA. Nothing about who lives there, ever. Here is why that matters.
The whole thing, honestly
Seven stages from the first awkward phone call to the keys. Each one has the encouraging version and the fact people usually get wrong.
1–3 days
It feels backwards to call a bank before you have seen a single house. Do it anyway. Twenty minutes on the phone turns a vague hope into a number, and the number is what makes everything after this calm instead of frantic.
Worth knowing Pre-qualification is a conversation. Pre-approval is a lender pulling your credit and verifying income and assets — it is the one sellers take seriously, and it is what you will attach to an offer.
One evening
A lender will tell you the most you can borrow. That is not the same question as what you want to pay every month for thirty years. We will sit down and run the second number, which is the one that matters.
Worth knowing The payment is principal, interest, property tax, homeowner’s insurance, any HOA fee, and PMI if you put down under 20%. In Wake County the tax line alone is roughly 1% of the price a year.
2–8 weeks
This is the part everyone imagines. Expect the first three to recalibrate everything you thought you wanted — that is the job they are doing, and it is not wasted time.
Worth knowing Most of our buyers see between eight and fifteen homes in person. If you have seen thirty, something upstream is off, and it is usually the price band or the area, not you.
Same day
The nervous part. We will talk through price, timing and what to ask for, and we will tell you plainly when we think an offer is a stretch — including when the stretch is worth it.
Worth knowing In North Carolina you offer a Due Diligence Fee (paid to the seller, generally non-refundable) and an Earnest Money Deposit (held in escrow, refundable in most circumstances). They are different instruments and people conflate them constantly.
14–30 days
Your inspection window is the period where you can walk away for any reason. Use it hard. Get the general inspection, and get the specialist out for anything the general inspector flags.
Worth knowing If the appraisal comes in below the contract price, the gap is yours to cover in cash, renegotiate, or walk. Decide before you offer which of the three you would do.
3–4 weeks
The loan is being checked properly now. Your only job is to be boring: same job, same accounts, same debts. It is a strange few weeks of doing nothing on purpose.
Worth knowing Do not open a credit card, finance furniture, or move large sums between accounts. Lenders re-pull credit before closing, and a new tradeline can undo an approval this late.
One morning
You will sign more paper than you expect and it will take about an hour. Then an attorney records the deed, and the house is yours. We will be there, and we will bring something for the first night.
Worth knowing North Carolina closings are handled by an attorney, not a title company. Funds must be wired — and wire fraud is real, so verify the instructions by phone with a number you looked up yourself.
Six kinds of search
A brokerage demo would normally put six named families here with a quote and a week count each. All of that would be invented, so instead: the six shapes a search takes and what we actually do in each.
First home · one or two incomes · no equity to move
The loan maximum and the payment you want are different numbers
We start at the lender, not at a listing. What comes back is two numbers: the largest loan you could be approved for, and the monthly payment you would still be comfortable with in February when the heating bill lands. Those are rarely the same number, and the gap between them is where most first-time buyers get hurt. We search against the second one. Every home on this site has a payment estimator on its page that shows principal, interest, tax, insurance and any HOA together, because the mortgage payment is not the cost of the house.
Usually Nadia — first-time buyers.
Moving in · short timeline · touring from another state
Ruling homes out before you spend a Saturday on them
The scarce thing is not homes, it is your Saturdays. So the first pass is done on video, on a call, with the map open and the commute drawn on it — and most of it is ruling places out. By the time you fly in, the list is short enough to see in a day and you already know why each one is on it. We will also introduce you to a lender before you write, because on a compressed timeline the ability to close quickly is worth more in a negotiation than another few thousand on the price.
Usually Priya — relocation and north Wake.
Growing family · trading up · one thing on the list is not negotiable
Drive the geography before you look at a single listing
The Triangle does not fit together the way a map suggests, and the honest first step is two hours in a car looking at nothing for sale. Once you can picture the distances, the search stops being a list of compromises and becomes one question: which single thing are you not giving up? A fenced yard, a main-floor bedroom, a garage you can actually park in. We build the filter around that one and let everything else move.
Usually Devon — new construction and the southern towns.
Downsizing · selling a long-held house first · stairs are the reason
Read the reserve study before you fall in love with the building
Selling a house you have owned for twenty-six years is not the same job as selling one you bought five years ago, and the order matters: what the sale nets you sets the budget for what comes next. On the buying side, a condominium is a share of a building and of its liabilities. We read the reserve study, the last two budgets and three years of minutes before we let anyone write an offer, because a thin reserve on a building with an ageing roof is a special assessment that has not been scheduled yet.
Usually Rosalind — downsizing and relocation.
Wants a project · has a design in mind · needs the budget to survive it
A renovation loan folds the work into the mortgage
Most searches quietly steer toward move-in-ready because it is easier to sell. If you want the opposite, say so and we will start sending you the listings other people skip. The financing is the part that decides whether it works: an FHA 203(k) or a conventional renovation loan folds the work into the mortgage rather than onto a credit card, but it comes with a draw schedule, a contractor bid and an inspection at each stage. We will sit in those meetings with you.
Usually Priya — relocation and north Wake.
Buying new · builder-held inventory or to-be-built
Negotiate the incentives, not the sticker
Builders protect the headline price because it sets the comparable for the rest of the phase. What moves instead is everything around it: closing-cost assistance, a rate buy-down through the preferred lender, an options allowance. We will run the buy-down against a straight conventional loan and show you the real cost of each rather than the monthly payment on the brochure. And we book an independent inspection before the eleventh month of the builder warranty, every time.
Usually Devon — new construction and the southern towns.
Composite descriptions of how a search is run, not testimonials. No client is described, no outcome is claimed and no duration is promised — there are no clients, because this is a demonstration site.
No pressure, genuinely
Twenty minutes on the phone, no obligation, no email sequence afterwards. If it turns out you should wait a year, we will tell you that — we would rather be the people you call in a year than the people who pushed you now.
Paint deck
Five schemes. Each one was measured against both themes before it was offered — text clears 4.6:1 on every surface in light and in dark. Your choice is remembered in this browser.
These settings are stored in this browser only. Nothing is sent anywhere. This site has not been through a formal accessibility audit, so it claims no conformance level — if something here does not work for you, tell us and we will fix it.
Four settings live in this browser. Your theme, your colour scheme, your reading settings and this answer — and nothing else. No cookies, no analytics, no advertising, no third parties, nothing sent to a server.Why.
Internal
Everything a visitor does not get: type, identity, logo and free colour. A visitor sees the paint deck in the bottom-left corner and only that.